Key takeaways
- Kevin Warsh tells House lawmakers the Federal Reserve does not want to rescue failing Bitcoin and crypto firms
- Warsh preserves discretion to mitigate extraordinary systemic risks, so his tough talk against bailouts stops short of an absolute pledge
- The Federal Reserve still decides when private losses threaten the wider system and justify support from its own balance sheet
A hard line with a qualification
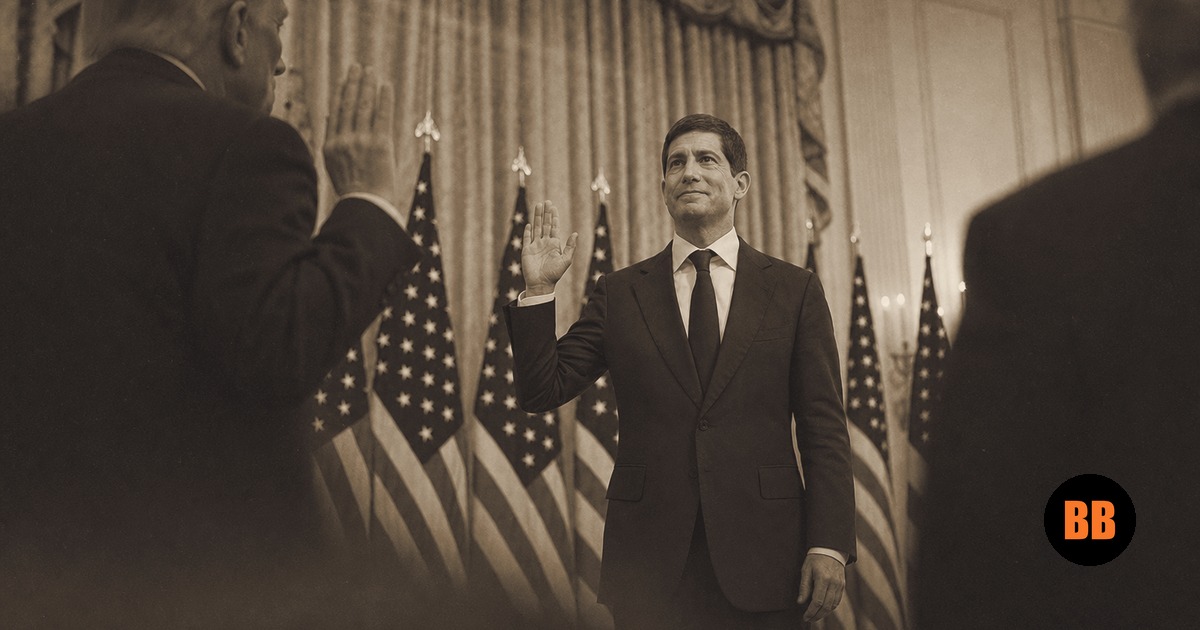
Federal Reserve Chairman Kevin Warsh told the House Financial Services Committee on July 14 that the central bank does not want to rescue failing Bitcoin and crypto firms. It was his first semiannual monetary policy testimony as chairman, and the exchange set market discipline beside the Fed's mandate to protect financial stability during market stress.
Representative Brad Sherman, a California Democrat and longtime critic of the industry, asked whether the Fed would backstop digital asset firms during a crisis as it supported money market funds in 2008. Warsh rejected the premise and linked his answer to the moral hazard created when investors expect public protection from private risk.
"We want to be in a position where we're not bailing out anybody, including crypto," Warsh told lawmakers.
Warsh has direct experience with crisis intervention. He served as a Fed governor during the 2008 financial crisis, and helped shape emergency measures under Chairman Ben Bernanke. In his testimony, he said he still carried the scars of that episode, and did not want to repeat it.
The Fed kept its emergency door open
The sharp language stopped short of an unconditional promise. Warsh also said the Fed would act to mitigate extraordinary systemic risks. That preserves the central bank's discretion if officials judge that one firm's collapse could damage markets, banks, or the payment system.
That qualification changes the meaning of the headline. Firms cannot count on routine support, but taxpayers cannot assume the bailout machinery has been dismantled. The same institution that defines systemic risk also controls emergency lending tools and a balance sheet measured in trillions of dollars.
The distinction is especially relevant as stablecoins and large trading platforms become more entangled with banks and payment networks. A rescue may be described as protecting liquidity or containing contagion rather than saving an individual company. The label changes more easily than the transfer of risk.
Why It Matters
Central banks create a recurring incentive problem: private actors keep the gains during easy conditions, then argue everyone will suffer once leverage unwinds. Warsh's rhetoric recognizes the moral hazard, but his systemic risk qualification preserves the same judgment call behind past interventions (the same discretion the Fed reached for last time). Bitcoin removes that discretionary backstop from monetary settlement entirely. Its rules cannot expand a balance sheet, invent emergency collateral, or socialize one institution's losses, so a market built on Bitcoin can fail without a committee deciding which balance sheet deserves rescue.